AI infrastructure
The physical foundation of compute.
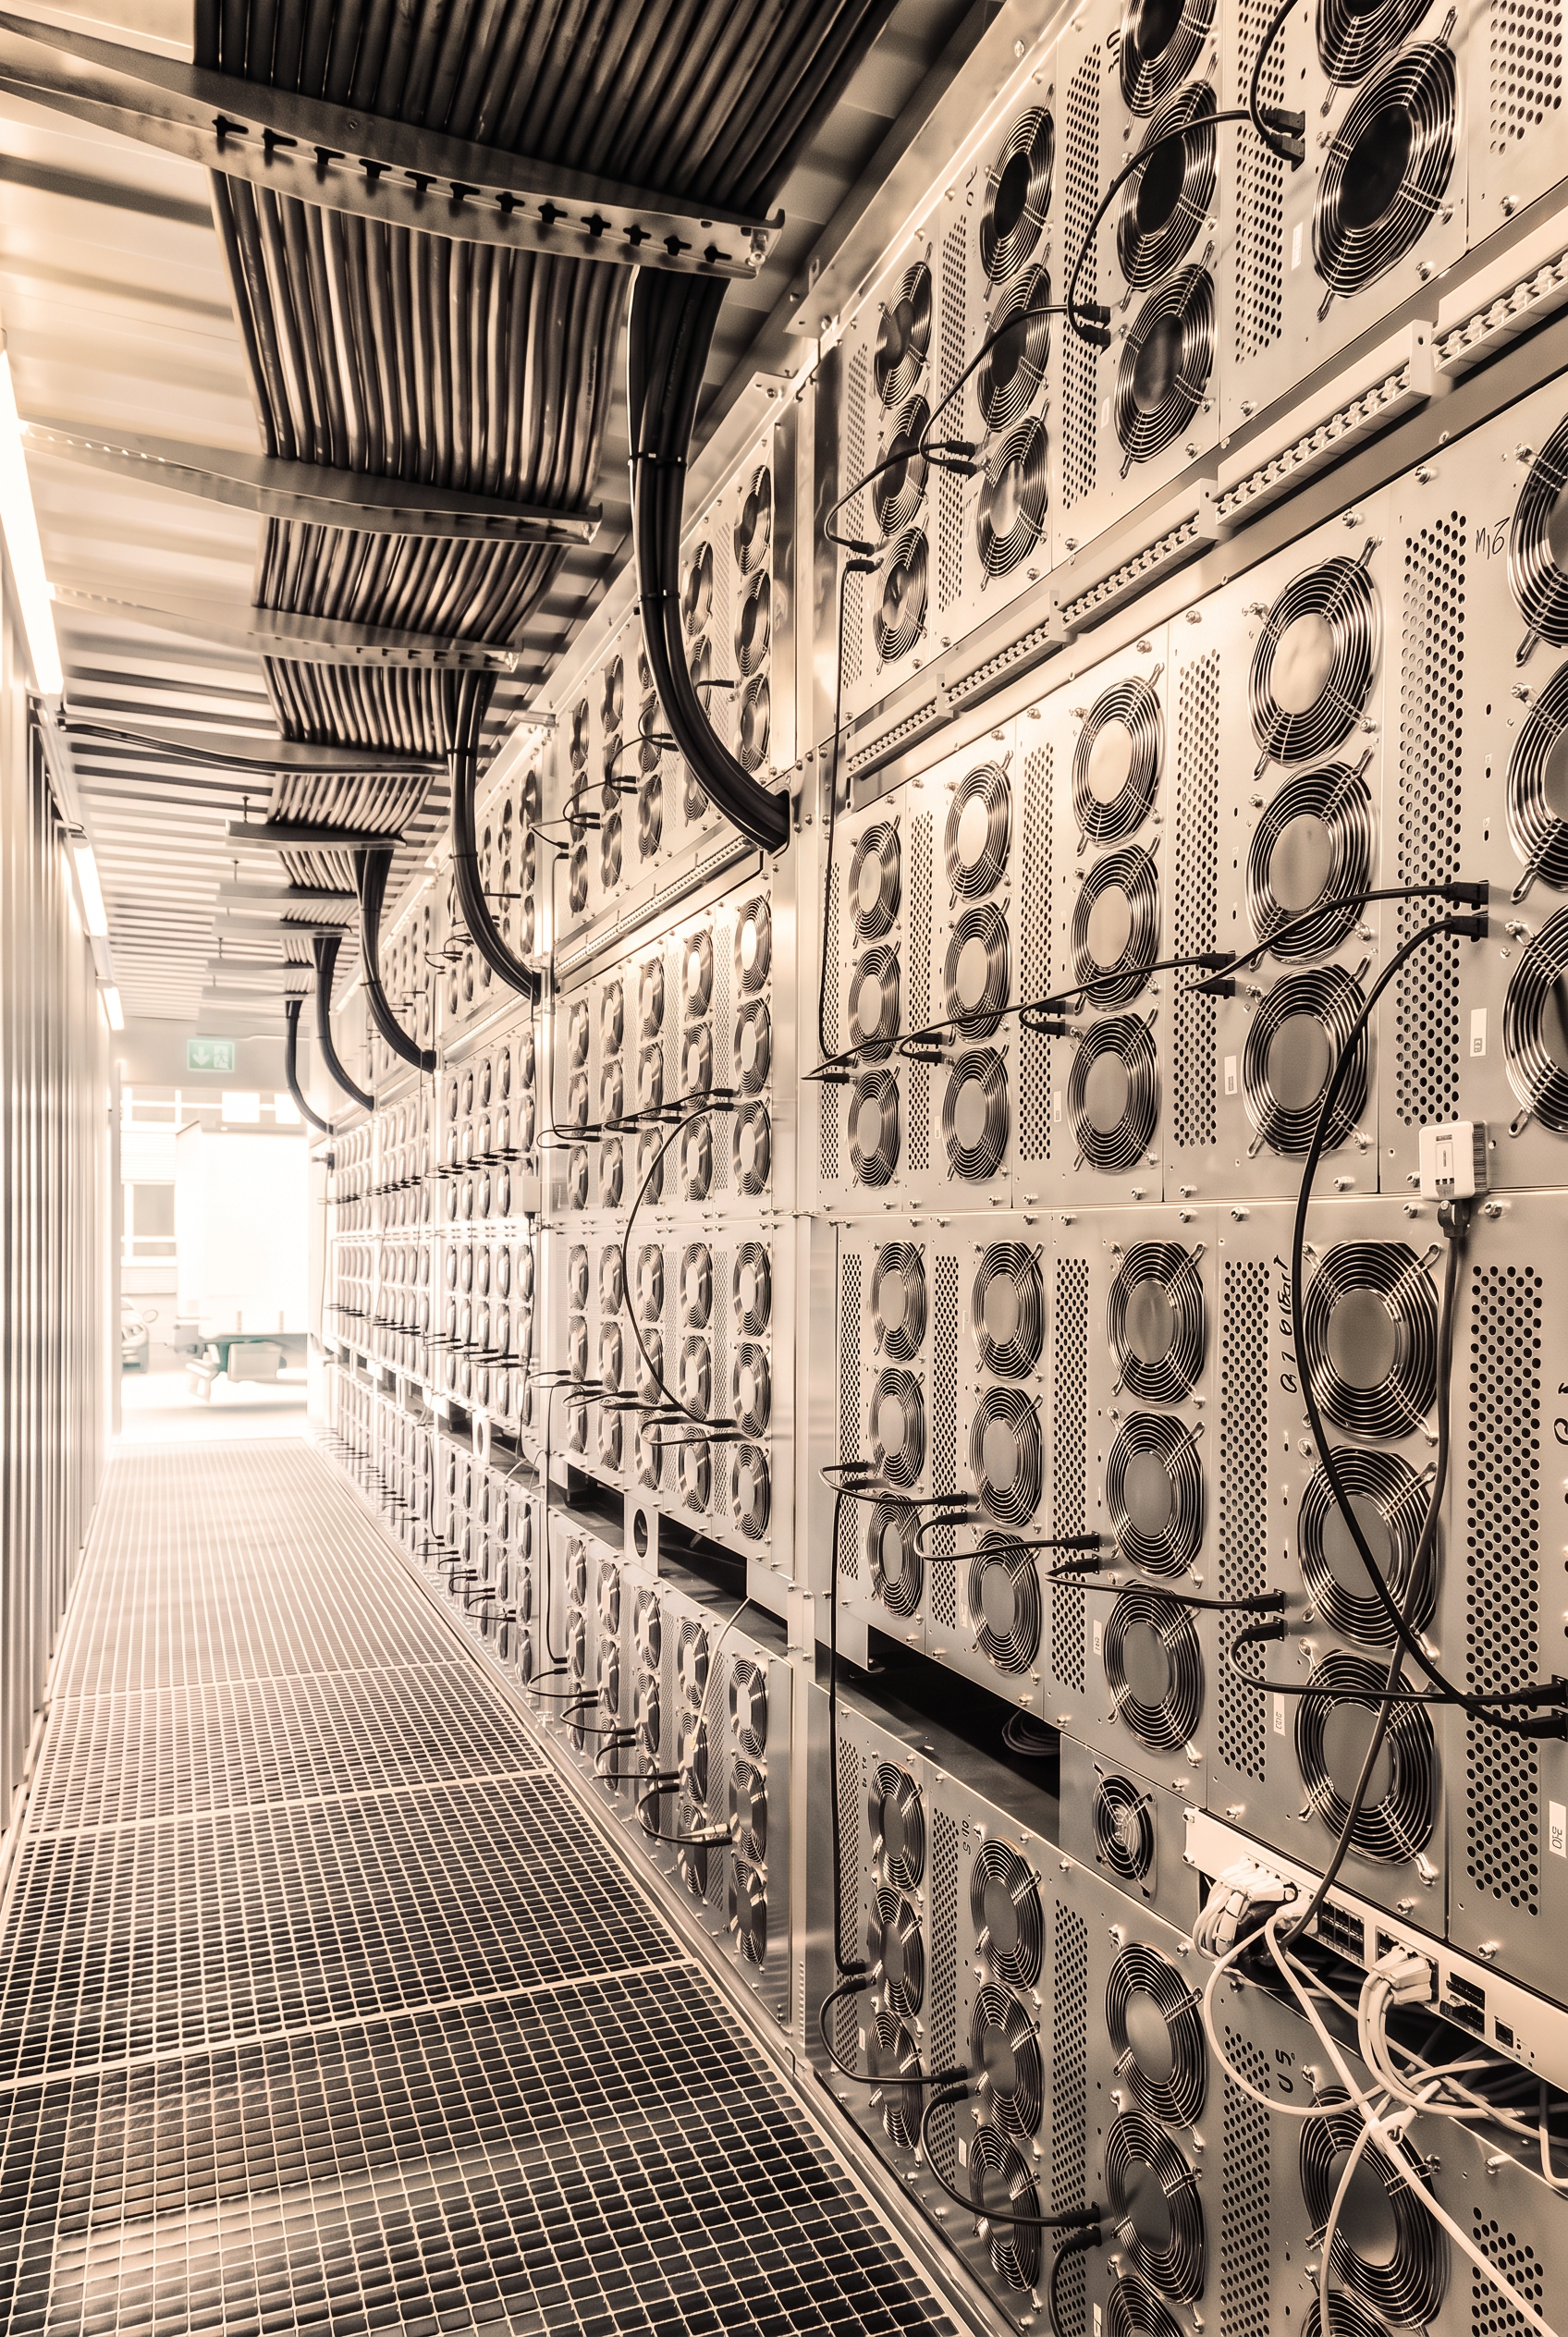
GPI identifies and advances the real estate, power and infrastructure required for data centers and AI compute.
Our strategy
Start with the physical constraints.
Location, power, connectivity and development execution determine what is possible. GPI approaches AI infrastructure first as a real estate and infrastructure discipline.
Market intelligence · Germany 2026
Germany Data Centers:
Operational Capacity vs New Builds
Selected major operational markets and announced / under-construction projects
Operational data center market
Capacity shown in MW of operational IT capacity
New / planned / under-construction project
Capacity shown using the source unit, either MW or MVA
Energy-intensive industry anchor
Tesla Gigafactory Berlin-Brandenburg, Grünheide — vehicle and battery plant, not a data center
Select a blue circle or orange diamond for market and project details.
Berlin / Brandenburg — Detail
Select any marker to review its status, capacity and expected timing.
Market insight
Germany’s data center market is expanding beyond Frankfurt.
Power availability, grid connection timing and access to suitable industrial land are increasingly determining where the next generation of AI and cloud infrastructure will be built.
Capacities are shown as reported by their respective sources. MW and MVA are not directly equivalent and are not visually presented as the same measurement.
Sources
- JLL, “Die neue Geografie des Rechenzentrumsmarktes in Deutschland”, April 2026.
- PwC Germany, “Data Center als neue Assetklasse”, project pipeline as of March 2026.
- German Datacenter Association, Datacenter Outlook Germany 2026/27.
Market and project data
- Frankfurt / Rhine-Main: Major operational market; Operational; 997 MW operational IT capacity.
- Berlin: Major operational market; Operational; 136 MW operational IT capacity.
- Munich: Major operational market; Operational; 102 MW operational IT capacity.
- Cologne / Düsseldorf: Major operational market; Operational; 55 MW operational IT capacity.
- Lippetal / Hamm: Blackstone Hyperscaler Campus; Under Construction; 200 MW; Completion expected early 2030s.
- Nierstein / Rhein-Selz: NTT Global Data Centers FRA6; Under Construction; 482 MW; Partial operation expected 2029.
- Lübbenau: Schwarz Digits Data Center; Under Construction; 200 MVA; Completion: end 2027.
- Lichterfeld-Schacksdorf: Project Jupiter; Planned; 500 MVA; Construction start: end 2026 / early 2027.
- Frankfurt (Oder): FFO AI Campus; Planned; 350 MW; Construction start: end 2028.
- Berlin Marienpark: VIRTUS Marienpark Campus; Under Construction; 57 MW; First building completion: Q3 2026.
- Berlin region: Vantage BER1; Planned; 56 MW; Expansion potential: over 300 MVA · Grid connection targeted by 2029.
- Wustermark: VIRTUS Megacampus; Under Construction; 300 MVA; Completion: 2026.
- Nauen: maincubes BER02; Under Construction; 200 MVA; First building completion: end 2027.
- Tesla Gigafactory Berlin-Brandenburg, Grünheide: Energy-intensive industry anchor. Not a data center. Vehicle and battery manufacturing plant, shown as an energy-intensive industry anchor. It is not a data center and no data center capacity is published for the site.
Powered assets
Land and buildings aligned with power.
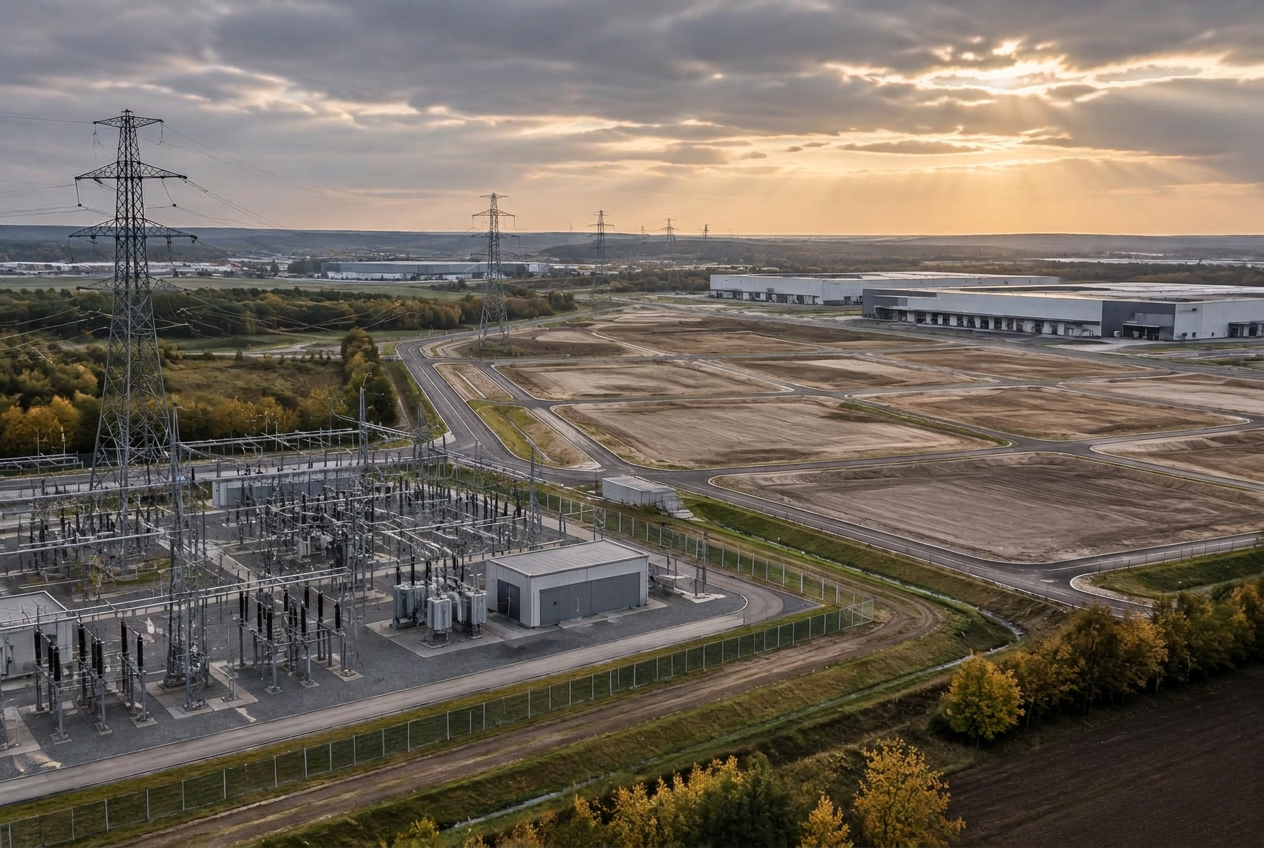
Power availability has become a defining real estate consideration. We assess sites through the combined lens of land, grid context, access and development potential.
Development
From site to operating infrastructure.
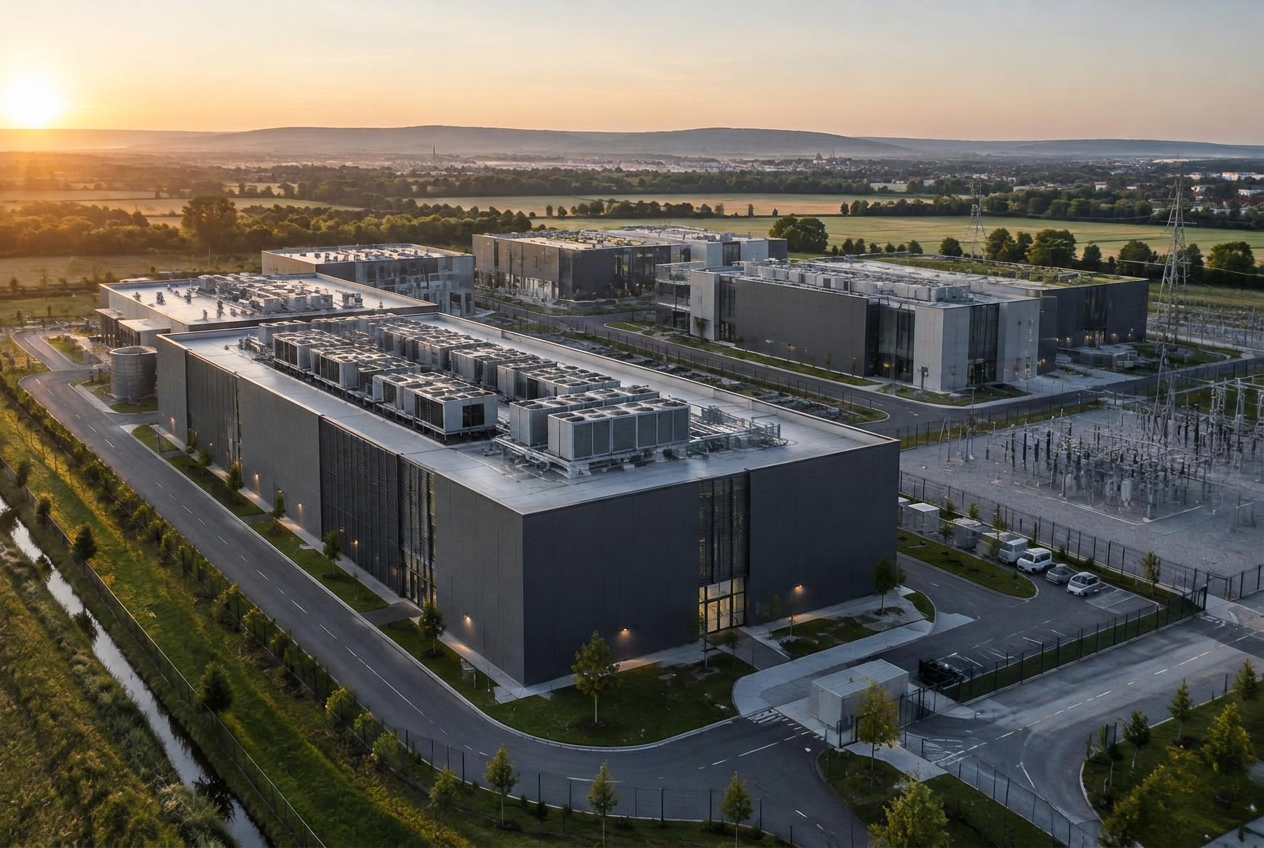
GPI’s role is grounded in the property lifecycle: sourcing, assessing, structuring and progressing sites for long-term infrastructure use.
Start a conversation